Categories
Community, Homebuyers, Homeowners, SellersPublished October 13, 2026
Should I Sell My Home If I Have a Low Interest Rate?
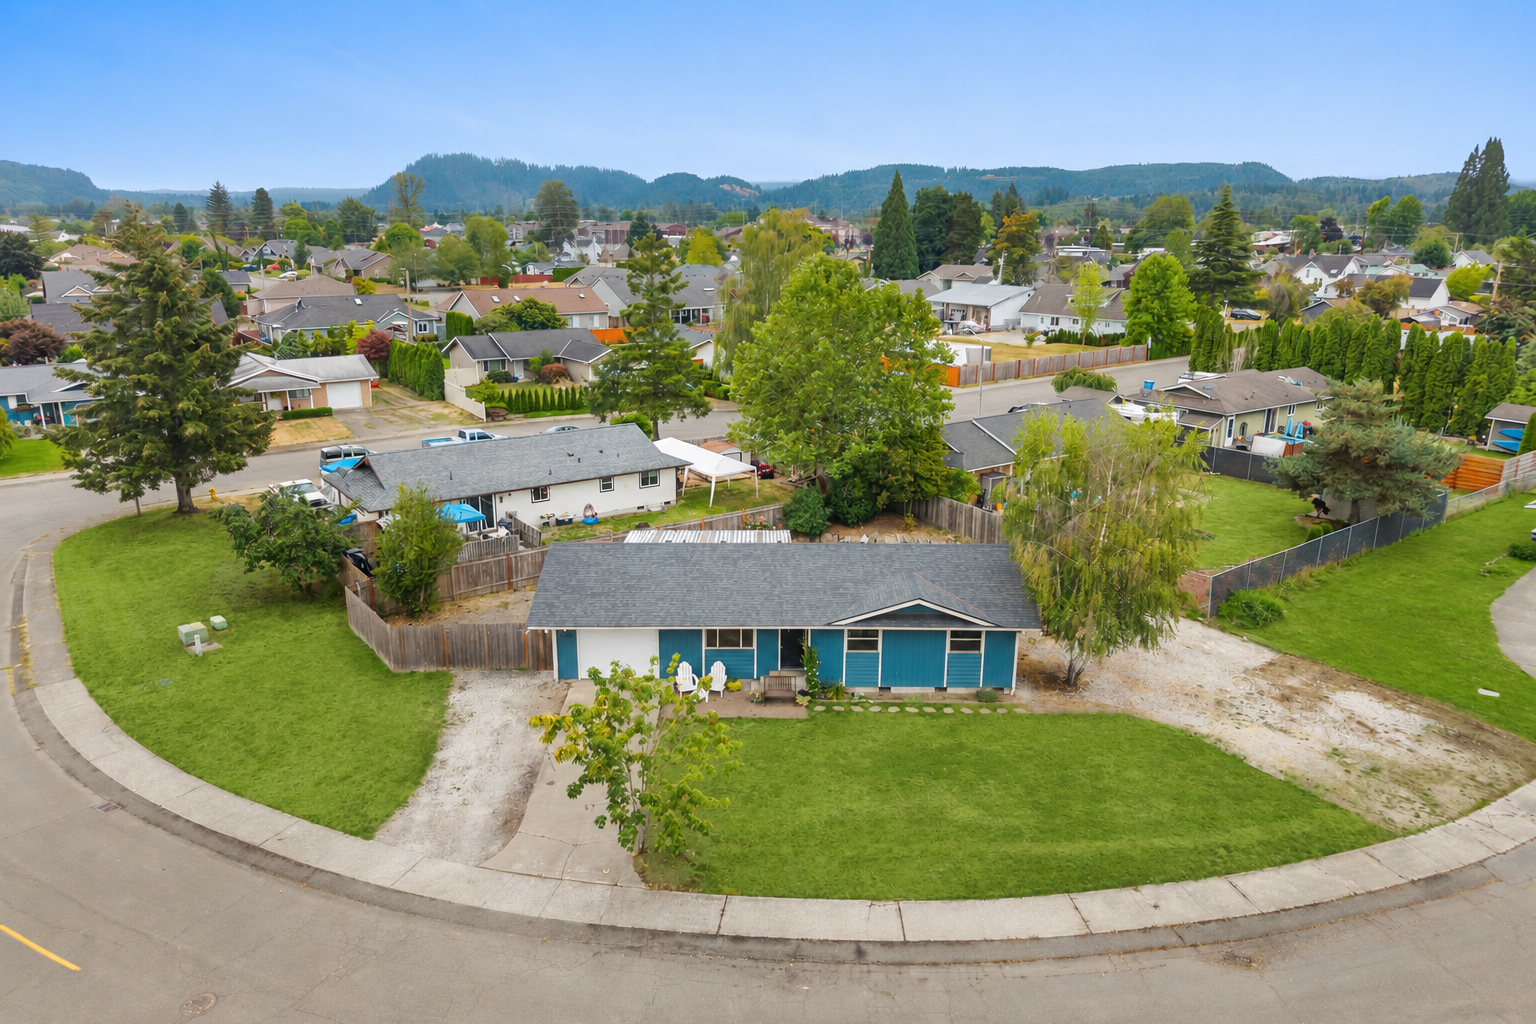
"My interest rate is 3%. Why would I ever move?"
It's a fair question. If you locked in a mortgage rate during 2020 or 2021, you're holding onto something pretty valuable. With today's mortgage rates considerably higher, selling your home and taking on a new mortgage can mean paying a higher interest rate, even if you're borrowing the same amount. So yes, that 3% rate matters.
But your interest rate is one number in a much bigger equation. When I sit down with homeowners in Auburn, Bonney Lake, Buckley, Lake Tapps, and the surrounding areas and we actually look at the cost of staying versus the cost of moving, sometimes the numbers are different than they expected.
Your Mortgage Payment Isn't Your Only Housing Cost
A low monthly mortgage payment feels great, but your mortgage isn't the only thing your house costs you. There are property taxes, homeowners insurance, utilities, yard maintenance, and the regular expenses that come with owning a home. Those costs can change over time even when your mortgage rate doesn't.
Then there are the bigger expenses that don't show up every month. How old is your roof? What about the furnace or heat pump? Are there windows that will need to be replaced? Is there exterior work you've been putting off? Maybe you're maintaining a large yard, paying to heat and cool rooms you rarely use, or looking at projects you know the house will need over the next several years.
None of that automatically means moving makes more financial sense. It just means that when you're deciding whether to stay because of your interest rate, we should be looking at the actual cost of staying, not only the mortgage payment.
What Would Moving Actually Look Like?
This is where I think the conversation gets more interesting. Instead of starting with today's interest rate and immediately deciding a move doesn't make sense, let's start with your actual numbers.
What could your current home sell for?
If you've owned your home for several years, there's a good chance you've built equity through a combination of appreciation, your original down payment, and paying down your mortgage.
How much equity would you have after selling?
Let's say you owe $250,000 on a home that could sell for $600,000. That's $350,000 in equity before accounting for the costs associated with selling. That equity becomes an important part of the next calculation.
What are you buying next?
If you're selling a $600,000 home and buying another $600,000 home, today's interest rate is obviously going to have a significant effect on your payment. But what if you're downsizing?
If your next home costs $400,000 and you're able to use a substantial portion of your equity toward the purchase, the amount you're actually financing could be dramatically smaller than the mortgage you have today. Suddenly, we're not comparing a 3% mortgage with a 6%+ mortgage on the same amount of money. We're comparing two completely different financial pictures.
Your 3% Interest Rate Is Valuable, But It Isn't the Only Number
This is the part I don't want homeowners to lose sight of. Your low interest rate is an asset. I would never tell someone to give that up without understanding exactly what they're gaining in return.
But your interest rate doesn't know that you don't want to maintain an acre anymore. It doesn't know that three bedrooms sit empty. It doesn't know that you'd rather be 10 minutes from your grandkids instead of 45. It doesn't know you're tired of stairs, want to travel more, would rather live closer to town, or simply don't want the responsibility that comes with your current home anymore.
Those things matter too. There are financial reasons for owning a home, but there's also the very practical question of whether the home still works for the life you're living now.
Sometimes Staying Really Is the Better Choice
There is absolutely a version of this conversation where we run the numbers and the answer is: stay right where you are. If you love your home, your expenses are manageable, the property still fits your life, and you don't have a compelling reason to move, holding onto a great mortgage rate can make a lot of sense.
I'm not interested in talking someone into selling a house they shouldn't sell. What I don't want is for someone to spend years assuming they can't move because they have a low interest rate without ever finding out whether that's actually true.
"I have a 3% rate" and "staying here is the best financial decision for me" aren't necessarily the same thing. Sometimes they are. Sometimes they're not.
Compare the Cost of Staying With the Cost of Moving
If you've been thinking about selling but your interest rate keeps stopping the conversation, we can start by running the numbers. We'll look at what your home could realistically sell for in today's market, approximately how much equity you have, what you're considering buying next, and what those two scenarios could look like side by side. From there, you can talk with your lender or financial advisor about the financing and determine whether moving actually makes sense.
Maybe the answer is to sell. Maybe the answer is to stay. Either way, I'd rather you make that decision with real information than let one number make it for you.
Schedule a time on my calendar, and let's look at what the numbers could actually look like for you. If you don't see a time that works for you, simply reply and let me know. We'll find a time that fits your schedule.
Larissa Butler
| Larissa Butler Realty | Keller Williams Realty Puyallup
or another way